Total loss by formula
Car insurance claim rules in New Mexico
What New Mexico law expects of an insurer handling your claim, how a car becomes a total loss, the crash reports drivers must make, and the time limits to sue.
By Valoroath Editorial Team Updated 6 min read
In plain terms
New Mexico's insurance code sets few day counts for routine claims. It requires insurers to act reasonably promptly and to affirm or deny within a reasonable time after proof of loss, and an insurer that leaves an amount justly due unpaid for 45 days after proof of loss owes interest at 1.5 times the state's bank prime rate. There is no damage percentage for a total loss. Drivers must call the police at once and file a written report with the Department of Transportation within 5 days after a crash with an injury or $500 or more of damage. You have 3 years to sue for injury and 4 years for property damage.
- Total loss rule
- Insurer's formula, no %
- Insurer must decide
- Pay in 45 days or interest
- Deadline to sue
- 3 yrs injury, 4 property
- Fault system
- At-fault
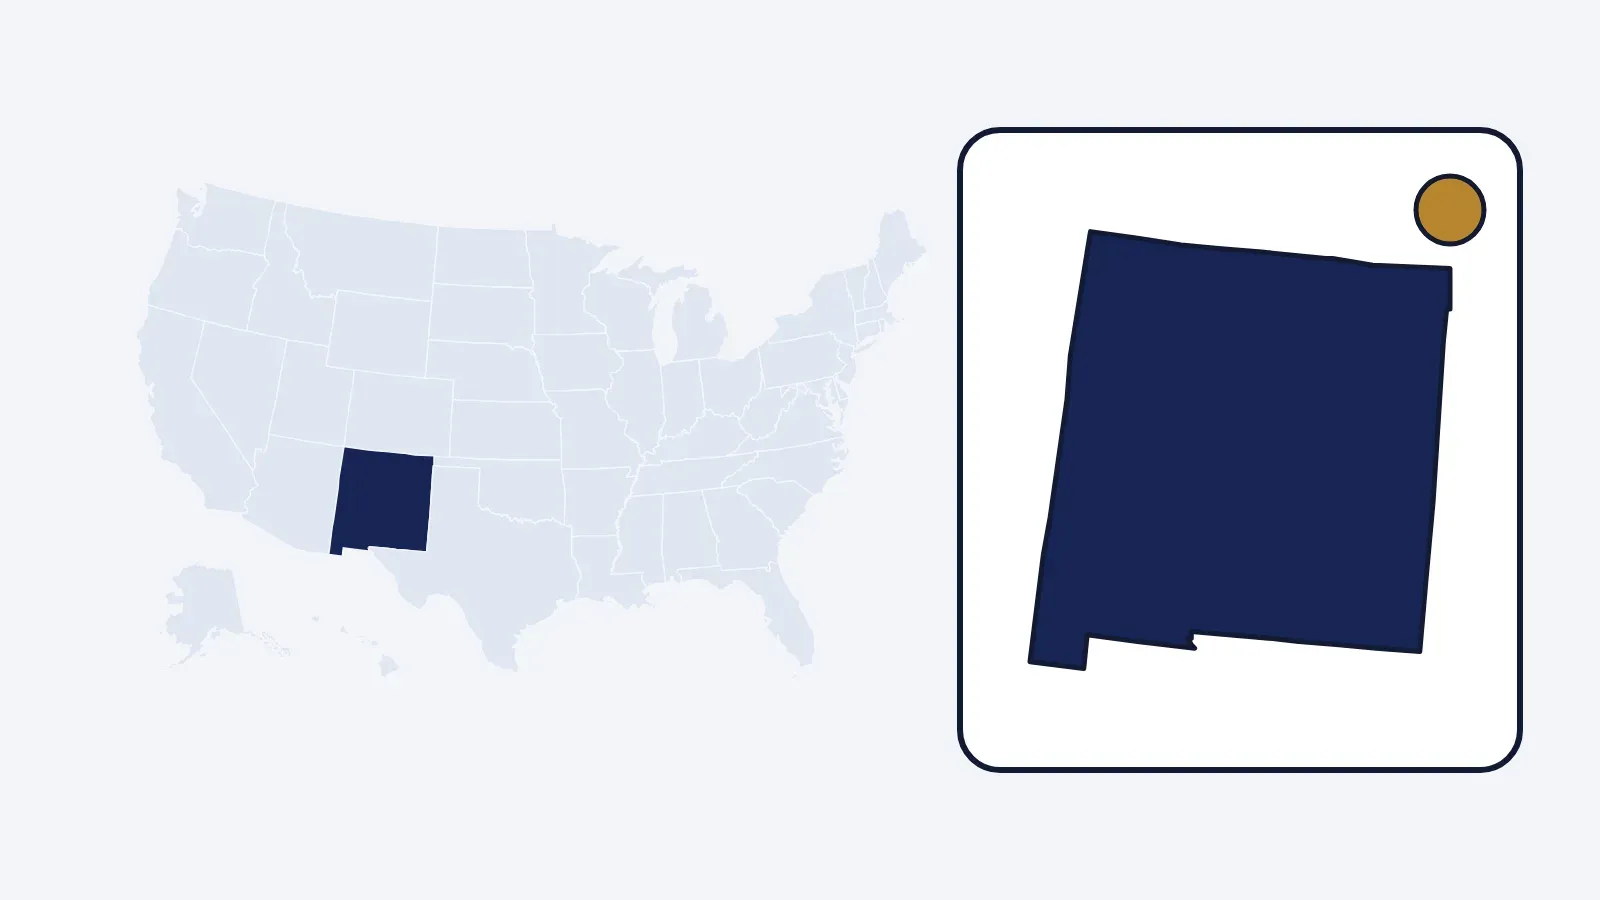
New Mexico claim rules on one sheet
- Total loss rule No percentage in law; insurer's formula Title law (NMSA §66-1-4.16): 'uneconomical to repair'. Hail damage is excluded under department rules.
- Insurer must acknowledge No fixed number; 'reasonably promptly' (statute)
- Insurer must decide Reasonable time after proof of loss; interest if unpaid at 45 days Interest at 1.5 times NM bank prime rate (NMSA §59A-16-21). Declared catastrophes: settle in 90 days.
- Deadline to sue 3 years for injury; 4 years for property damage
- Fault system At-fault; pure comparative negligence
- Police report needed At once for injury, death or apparent damage of $500 or more
- State crash report Driver's written report to NMDOT within 5 days (same thresholds) Required by NMSA §66-7-207 even when police respond; officers also file their own reports.
A summary by Valoroath of the state's statutes and regulations, not an official document. The sources are listed at the end of this page.
What the insurer owes you on timing
Section 59A-16-20 of the New Mexico Insurance Code lists unfair claim practices. Among them: failing to acknowledge and act reasonably promptly on communications about claims, failing to affirm or deny coverage within a reasonable time after you complete the proof of loss, and failing to try in good faith to settle once liability is reasonably clear. The statute uses no day counts for those steps.
| Rule | What it requires | Source |
|---|---|---|
| Acknowledge and act on communications | Reasonably promptly | NMSA §59A-16-20(B) |
| Affirm or deny coverage | Within a reasonable time after proof of loss | NMSA §59A-16-20(D) |
| Pay the amount justly due | 45 days after proof of loss, or interest runs | NMSA §59A-16-21(B) |
| Catastrophe claims, including car damage | Settle within 90 days of the declaration | 13.7.4 NMAC |
The interest is 1.5 times the prime lending rate for New Mexico banks, fixed on the 46th day after proof of loss. It does not apply to claims already in arbitration or litigation. Send your proof of loss in a way that shows the date it arrived, since that date starts the clock. For a file that stalls, see our page on slow claims.
Total loss in New Mexico
New Mexico's title law, NMSA §66-1-4.16, has no repair-cost percentage. A car becomes a salvage vehicle when the insurer, owner or lender considers it uneconomical to repair. A car the insurer pays as a total loss gets a branded salvage title even if it is later fixed, once you agree to the settlement amount and the insurer tells you the title must be branded. Under the department's rules, hail damage is left out when deciding salvage status.
- The insurer's math decides. Most insurers compare the repair estimate plus the car's salvage value with its actual cash value.
- The payment is actual cash value. Ask for the valuation report and the comparable cars it used; our guide to total loss claims lists what to check.
- Run the numbers yourself. The total loss check shows how a formula state reaches its decision.
Reporting a New Mexico crash
Under NMSA §66-7-206, a driver in a crash that injures or kills someone, or causes apparent property damage of $500 or more, must notify the police immediately by the quickest means: the city police inside a municipality, otherwise the county sheriff or the nearest New Mexico State Police office.
New Mexico also requires the driver's own written report. Section 66-7-207 says the driver must send it to the Department of Transportation within 5 days after a crash with an injury, a death or total property damage of $500 or more. Officers who investigate send their own reports within 24 hours after finishing. Keep a copy of what you file for your insurer.
Fault and shared blame
New Mexico is an at-fault state, so the driver who caused the crash and their liability insurer pay for the damage and injuries they caused. In Scott v. Rizzo (1981), the New Mexico Supreme Court adopted pure comparative negligence: your own share of fault reduces what you recover but does not bar it, even if your share is the larger one.
If the other driver has no insurance or too little, your uninsured motorist coverage may pay; see a crash with an uninsured driver.
Deadlines to sue and where to complain
Under NMSA §37-1-8, a lawsuit for personal injury must be filed within 3 years. A suit for damage to your car or other property has 4 years under §37-1-4. Your policy may set its own time limits for notice and for disputes, so read its conditions.
- Put your questions in writing and ask for the policy language behind a denial or a low offer.
- Contact the Office of Superintendent of Insurance (OSI), which processes consumer complaints, holds hearings and resolves appeals.
- File a complaint with OSI if the insurer misses the 45-day payment rule or won't explain itself; see our guide to insurance department complaints.
Questions people ask
How long does an insurer have to pay a claim in New Mexico?
If an insurer fails for 45 days after proof of loss to pay the amount justly due, it owes that amount plus interest at 1.5 times the New Mexico bank prime rate under NMSA §59A-16-21. The law sets no day count for acknowledging a claim; it must act reasonably promptly.
What percentage of damage totals a car in New Mexico?
None is set in law. A car is a total loss when the insurer finds it uneconomical to repair, and it then gets a salvage title even if it is fixed later.
Do I have to file a crash report in New Mexico?
Yes, if anyone is hurt or killed or property damage reaches $500. Call the police immediately, and send a written report to the Department of Transportation within 5 days.
Can I recover if I was partly at fault in New Mexico?
Yes. New Mexico uses pure comparative negligence, so your recovery is reduced by your percentage of fault but not barred.
Sources on record
- NMSA §59A-16-20 — Unfair claims practices (2024 edition)
- NMSA §59A-16-21 — Interest on claims unpaid after 45 days (2025 edition)
- 13.7.4 NMAC — Catastrophic claims
- Office of Superintendent of Insurance — Bulletin 2022-005, interest on unpaid claims
- NMSA §66-1-4.16 — Definitions, salvage vehicle (2025 edition)
- NMSA §66-7-206 — Immediate notice of accidents (2025 edition)
- NMSA §66-7-207 — Written reports of accidents (2025 edition)
- Scott v. Rizzo, 1981-NMSC-021 — Adoption of pure comparative negligence
- NMSA §37-1-8 and §37-1-4 — Limitations for injury and property (2025 edition)
- New Mexico Office of Superintendent of Insurance
Facts on this page were checked against these sources on November 11, 2026. The OSI bulletin linked above has since been superseded; the interest formula itself is set by NMSA §59A-16-21.
Ask a licensed agent to review your coverage
After a claim, the policy you had is the one you can still change. Describe your situation and Valoroath passes it to licensed insurance agents and insurers who can review your coverage and quote, if you want them to. Valoroath itself does not sell insurance or handle claims.
- 1 Five questions about your car, your record and your policy.
- 2 Who to ask for, and your consent to be contacted.
- 3 A licensed insurance agent or insurer reviews what you have. You change nothing unless you choose to.
Sending this request shares your answers and contact details with the licensed insurance agents and insurers who receive it, which some state privacy laws treat as a sale; see your privacy choices. An agent reviews your coverage; they can't take on your claim or a dispute with your insurer. You pay Valoroath nothing. The licensed insurance agents and insurers who contact you pay Valoroath for requests and set their own prices and terms; your claim stays with your insurer. How we make money.
Next in the file
-

How claims work
Total loss claims
When a car is totaled, what actual cash value should include, and what happens to the loan and the title.
-
Claim dispute
When your claim drags on
The time limits insurers work under, why files stall, and the written steps that move a claim.
-

After a crash
When to call the police
The cases for 911, state damage thresholds from $50 to $4,000, and why a report helps after a small crash.